Bank on My Terms
The Art of BankCraft™
Build Your Financial Symphony
Choose institutions for what they do best. Give each one a job. Test the connections. Build alternate routes. You are the conductor.
Last updated: August 30, 2026
A Discipline, Not A Product
The Art Of BankCraft
Banking is not a product you choose once and live with forever. It is a system you design, test, and improve. The Art Of BankCraft is the deliberate practice of assigning each institution a job, understanding how money can move between them, and building alternate routes before one bank's limits, holds, or failures leave you trapped.
Every institution has strengths, limits, and blind spots. The craft is using its strengths, routing around its weaknesses, and making the entire banking system work for you.
Your Banking Ecosystem — Made Visible
Build Your Financial Symphony
Your banking ecosystem is your Financial Symphony.
Stop expecting one institution to play every part. Give each bank or credit union the chair it earns and let it perform the job it does best.
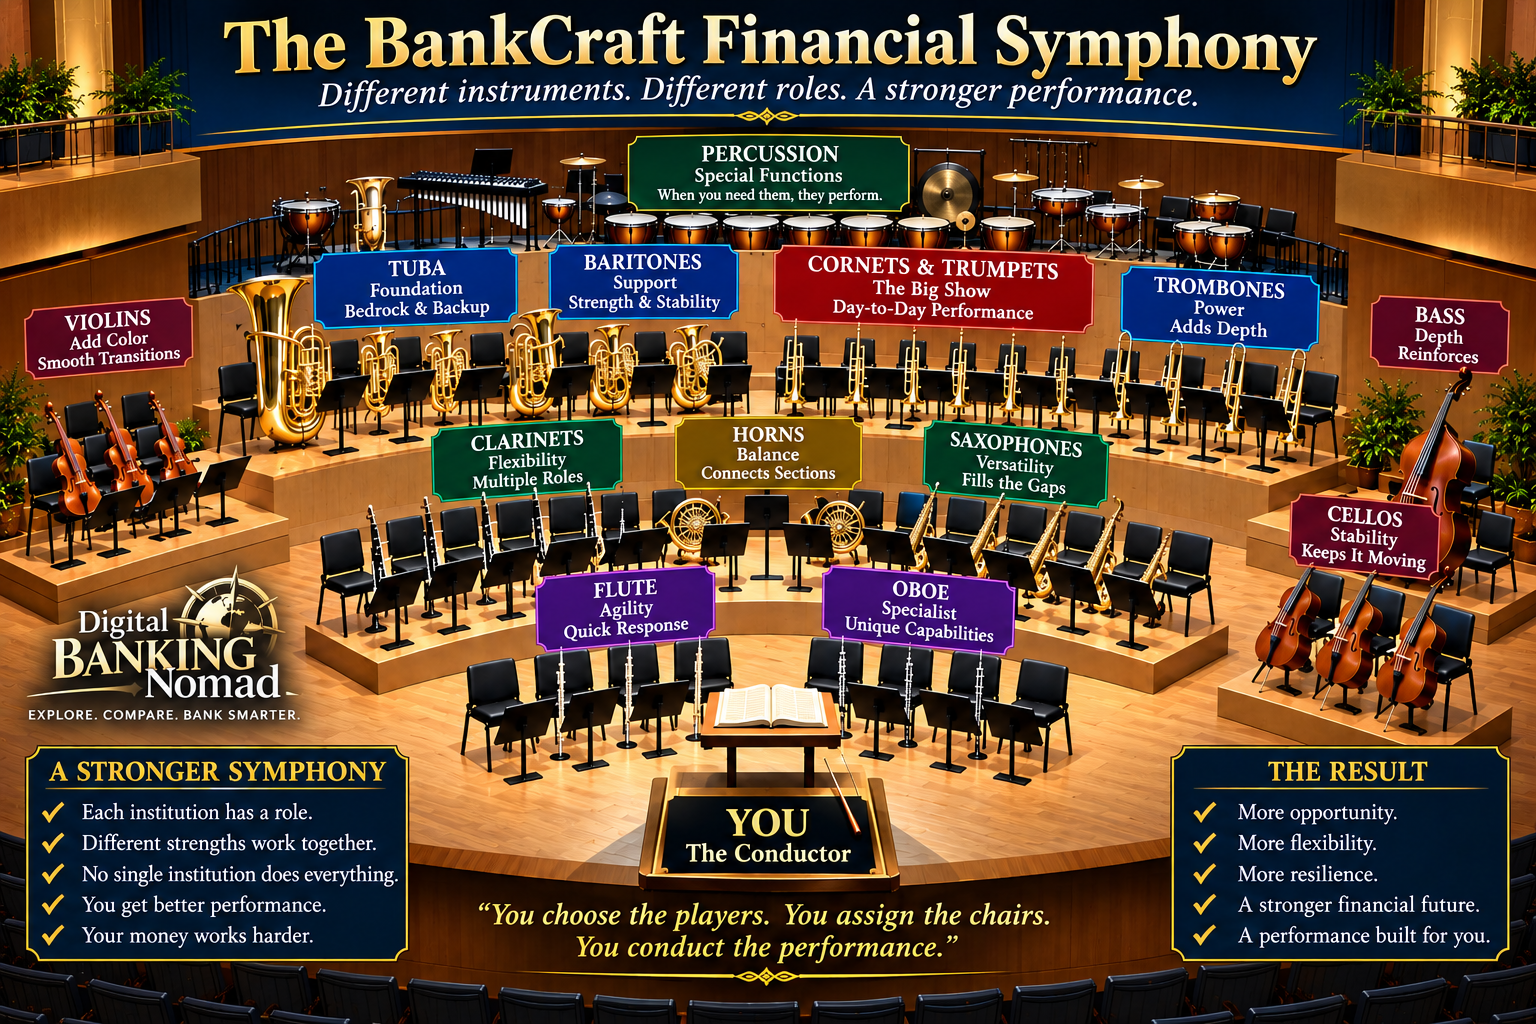
Anchor. Specialist. Active. Vault. Reserve. Benched. A ★ Bridge is a special capability that can connect parts of the Symphony that otherwise cannot reach one another.
You are the conductor. You decide who plays, who sits in reserve, who gets a solo—and when an institution needs to put its horn in the case and leave.
Don't let one institution turn your financial life into a one-trick pony when you can build a Symphony.
Like any strategic craft, it begins with knowing the terrain: which routes are open, where the chokepoints are, and what alternatives remain when the obvious path is blocked. This is not about collecting accounts for sport or chasing every shiny APY. It is about knowing your anchors, specialists, active players, vaults, reserves, bridges, transfer limits, and escape routes—and using them with purpose. That is The Art Of BankCraft.
For a simple address to this guide, use Bankcraft.us, Bankcraft.art, Bankcraft.net, TheArtOfBankcraft.com, or ArtOfBankcraft.com. Each address leads here.
Need a translation?
BankCraft has its own language, and banking has plenty of jargon of its own. The Glossary keeps the plain-English definitions in one place.
Open the BankCraft Glossary →What is a BankCraft Protocol?
A BankCraft Protocol is a repeatable way of handling a banking situation — what to check, what to do, how to do it, and what to watch for.
Learn about BankCraft Protocols →BankCraft 101
Cash back is an instrument, not a perk.
BankCraft is not only about where money sits or how it moves. It is also about what happens every time you spend it. The goal is not to find one “best” credit card. It is to give a small number of cards specific jobs and route each purchase through the instrument that performs that job best.
A 5% card is not automatically a rare luxury product, and it is not automatically the right card. The reward may apply only to gasoline, groceries, a mobile wallet, or one retailer. It may have a spending cap or qualification requirements. BankCraft means understanding those terms and deciding whether the card has a real assignment in your Financial Symphony.
The Gas Pump Test
5% cash back versus 5¢ off per gallon
A real fill-up used 14.74 gallons and cost $53.65, an average of approximately $3.64 per gallon. The advertised nickel sounds concrete. The percentage hides the larger result until you calculate it.
The 5% card returns more than three and a half times as much and produces an effective discount of approximately 18.2 cents per gallon. Even a 2% card would return about $1.07—roughly 7.3 cents per gallon—and beat the advertised nickel.
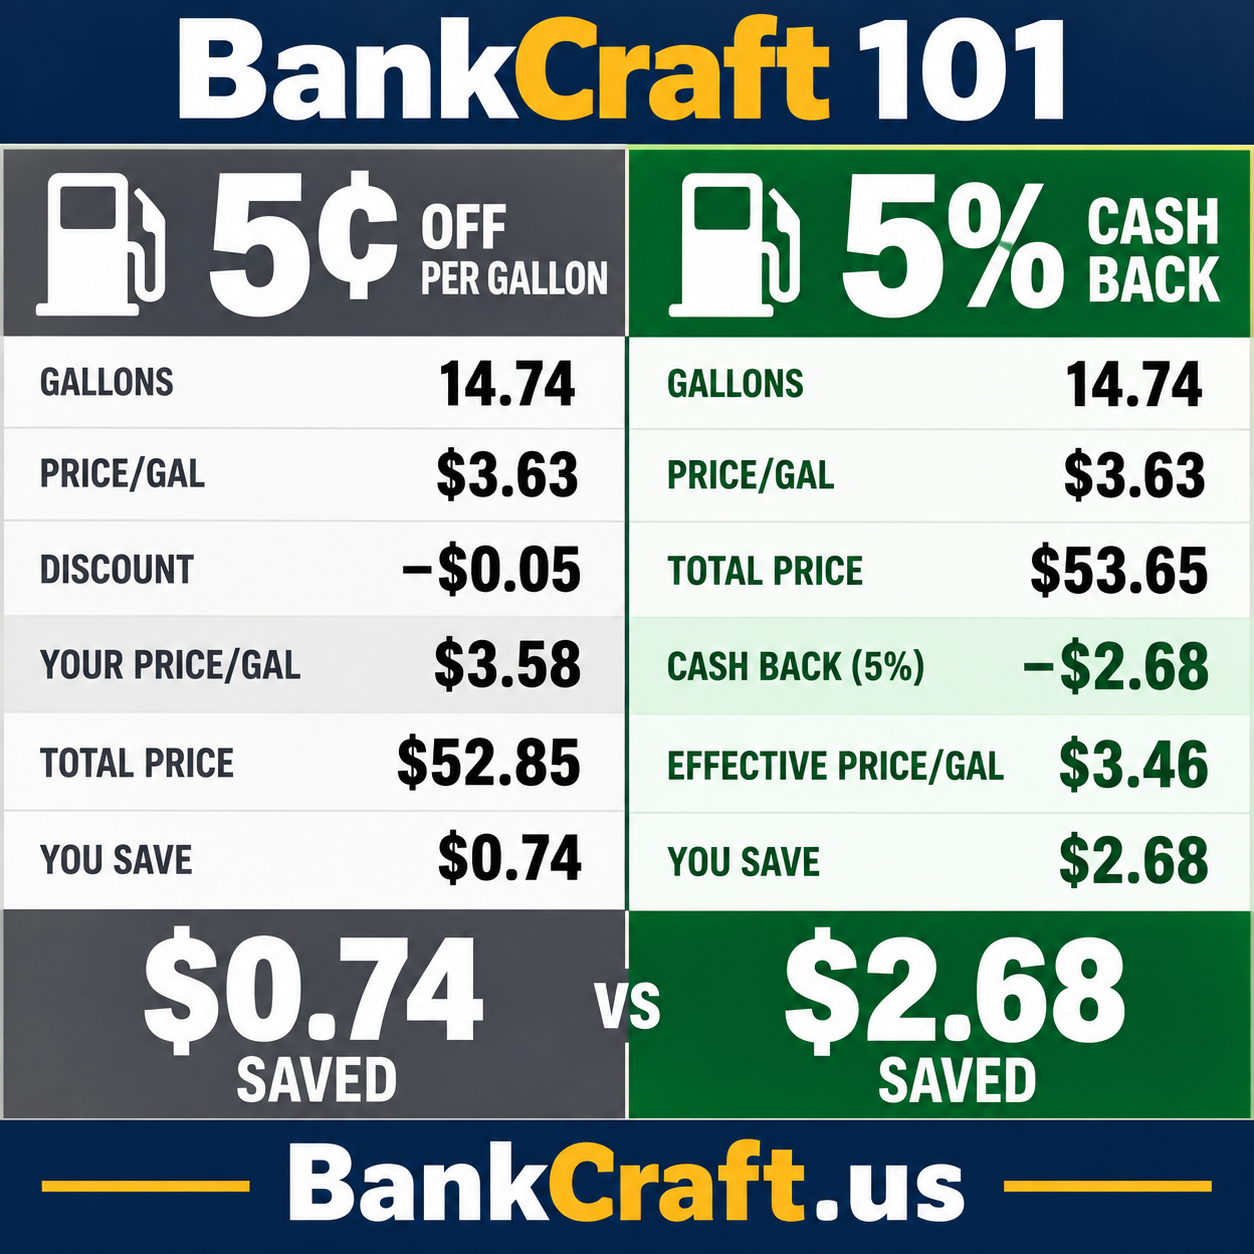
Do not compare the advertisements. Compare the math. Then assign the purchase to the card that does the job best.
The Nonnegotiable Rule: Pay It Off.
The coolest thing about a cash-back credit card is that you use their money for about 30 days—and then they pay you for using it. How sweet is that?
This is one of those rare times when you get to stick it to the man. This is one time when you win.
But there is one nonnegotiable rule: you must pay the card off completely.
If you do not pay it off completely, the interest can wipe out the reward—and you lose big.
If you cannot pay it off completely, you would be better off not using the card at all.
See the cards currently performing these jobs in D.B. Nomad's wallet.
The First Rule
Do not mistake a dashboard connection for a transfer connection.
An app may show the balance and transactions from another institution without giving you any way to send money there. Account aggregation, account verification, and money movement are related—but they are not the same job.
If you can see the account but cannot push to it, pull from it, or let a merchant debit it, you have information—not connectivity.
Core Bankcraft Principle
Improvise. Adapt. Overcome.
Do not confuse a blocked route with a dead end.
Banking systems are full of mismatched rules, incompatible connection methods, transfer caps, and institutions that simply do not play nicely with one another. When the obvious path fails, the answer is not always to give up on the account.
Adapt = change your banking setup to use that alternative.
Overcome = accomplish what you were trying to do anyway.
The practical question is not, “Why won’t this bank let me do what I want?” The better question is:
What other route can I build with the institutions I already control?
Real-world example: ValorFI, Abound, and EleVault
I wanted to use EleVault as the Vault in my Financial Symphony—a high-yield place to park cash. I was able to connect ValorFI from inside EleVault, but EleVault’s own transfer system was limited to $2,500. For moving any meaningful amount of money, that route was too restrictive.
I could have stopped there and said, “EleVault is useless.”
Instead, I stepped back and looked at the entire banking ecosystem.
Abound supports manual external-account linking through microdeposits. That gave me another way in. I linked EleVault from the Abound side.
Now the transfer was no longer controlled by EleVault’s $2,500 pathway. When I initiate the ACH from Abound, I am dealing with Abound’s transfer limits and rules instead.
EleVault did not change.
Its own transfer system did not improve.
I changed the route.
That first successful Abound connection changed the way I looked at EleVault. Instead of asking what EleVault itself would let me connect, I started asking a better question: What other institutions can connect to EleVault from their side?
The answer turned one restrictive pathway into a network. Charles Schwab, Axos Bank, Alliant Credit Union, and Abound Credit Union were each able to establish external ACH connections to EleVault using account verification and microdeposits.
EleVault still had the same two-link restriction and the same $2,500 native transfer path. Nothing inside EleVault changed. What changed was the Financial Symphony around it.
EleVault had two doors. The banking ecosystem gave it four bridges.
Improvise
The obvious ValorFI-to-EleVault path was too restrictive. So I looked for another institution that could establish the connection from its side.
Adapt
I changed the structure of the ecosystem and used Abound as the bridge because Abound could verify EleVault through microdeposits.
Overcome
I turned an account that looked impractical into a usable Vault—a place to park cash—by reaching it through a different pathway.
That is the larger lesson. If one institution cannot send money directly to another, do not automatically conclude that the destination is unreachable. Can the receiving institution pull it? Can another institution connect to both? Can you use microdeposits instead of Plaid? Can one of your existing accounts become the bridge?
A blocked route is not necessarily a dead end. Solving it is The Art Of BankCraft.
The Names You May Encounter
Plaid is not the only connector.
These are not different versions of Plaid. They are separate companies and networks that financial institutions and fintechs use to connect, verify, or retrieve information from outside accounts. You may see the provider’s name, its logo, a branded connection window—or no obvious identification at all.
Plaid
Plaid Link handles the account-linking experience, including institution search, credentials or OAuth handoff, multifactor authentication, errors, and account selection.
MX
MX provides account aggregation, ownership identification, balance checks, instant account verification, and microdeposit verification. The exact capability depends on what the institution purchased.
Mastercard Open Finance
Often still encountered through the Finicity name, Mastercard’s open-finance tools support permissioned data access, account verification, analytics, and some account-to-account payment uses.
Envestnet Yodlee
Yodlee’s account-aggregation and FastLink tools connect financial accounts and retrieve account and transaction information for financial applications.
Akoya
Akoya is an API-connected data-access network focused on permissioned financial-data sharing and giving consumers visibility and control over connected applications.
The Institution’s Own System
A bank may use its own digital-banking platform, a processor integration, or a mixture of services. The logo you see does not tell you every system operating behind the page.
The Bankcraft question is not “Which logo did I see?” It is “What does this connection actually let me do?”
Connection Methods
How an outside account gets linked.
OAuth or API connection
You are handed to your financial institution, sign in there, approve specific access, and return. The third-party app receives permissioned data rather than simply pretending to be you.
Credential-based linking
You enter online-banking credentials into a connection flow. The provider handles authentication and may need renewed credentials or multifactor approval when the connection breaks.
Routing number, account number, and microdeposits
You enter the account information manually. One or two small ACH entries arrive, and you confirm the amounts or verification information to prove control of the account.
Link from the other institution
If Bank A cannot add Bank B, Bank B may still be able to add Bank A. Which side initiates the transfer can completely change the available limit, hold, and success rate.
Manual linking is sometimes buried. A page may first show only a list of institutions, then reveal “Add manually” or “Don’t see your institution?” after you select or search. Do not assume the option is absent until you have looked through the complete flow.
Money Movement
Push and pull are two different trips.
The ACH network supports both credits and debits. In practical Bankcraft language, the difference is who receives your instruction.
PUSH → Send it
Start where the money is.
You tell the institution holding the funds to send them to the receiving account. The sending institution’s push limit controls the trip.
PULL ← Retrieve it
Start where the money is going.
You tell the receiving institution to retrieve funds from the outside account. The receiving institution’s pull limit and hold policy control the trip.
The same two accounts may support a $2,500 push in one direction and a $25,000 pull initiated from the other side. Always test both directions.
Bridges & Connectivity
Your bank is not your banking system.
Also ask what can connect to it.
Designing those pathways before you need them is The Art Of BankCraft.
Your banking system is the network of accounts and ACH pathways you control. One institution may hold most of your money. Another may barely be used at all. But that quiet account can still be extremely valuable if it gives you a working route to somewhere the first institution cannot reach.
Connectivity is a banking feature. An account can be strategically important even when almost no money stays there.
A failed Plaid connection is not necessarily a failed banking connection.
If Bank A cannot find Bank B through Plaid, do not stop there. Go to Bank B. Enter Bank A manually. Use the routing and account numbers. Look for microdeposits. If Bank B can verify Bank A, Bank B may be able to pull the money out even though Bank A could not send it there.
Build the bridge from the other side.
The money does not care which website you were logged into when the ACH instruction started. What matters is whether one of the institutions can originate the ACH transaction.
Microdeposits are more powerful than they look.
Plaid and instant verification are convenient when they work. When they do not, manual linking can be the escape route. A financial institution that allows routing-number and account-number entry with microdeposit verification can often connect to institutions that never appear in its instant-link search.
That is why “Plaid cannot find my bank” should never automatically become “I cannot move my money.”
A bridge account does not have to be your everyday bank.
It may sit almost empty. You may rarely log into it. You may never use its debit card. That does not make it useless. If it has good external-account connectivity, useful ACH limits, and reliable microdeposit verification, it can become critical infrastructure when another route fails.
Do not let one institution hold you hostage.
If your paycheck lands at one bank, your bills come from that bank, and every outside connection depends on that bank's transfer system, you have created a single point of failure.
A better banking ecosystem has more than one tested route. If one institution changes its rules, breaks its Plaid connection, lowers a transfer limit, blocks another bank, or simply becomes difficult to deal with, you already have another bridge.
That does not mean collecting accounts for sport. It means deliberately keeping useful pathways available before you need them.
Read the Fine Print
A transfer limit is never just one number.
When an institution says “$5,000 limit,” the next question is: $5,000 per what—and for which direction?
- Per transaction: the most allowed in one transfer.
- Per day: sometimes measured by initiation date and sometimes by posting date.
- Per calendar month: commonly resets on the first day of the month.
- Per rolling 30 days: looks backward from today or from transaction posting dates.
- Transaction count: the dollar limit may be generous while the number of transfers is tiny.
- Push versus pull: each direction may have a completely different ceiling.
- New-account limits: the institution may temporarily reduce access or place longer holds.
Arrival Is Not Availability
A posted deposit may still be held.
A deposit can appear in the account, begin earning interest, and still be unavailable for withdrawal. That is why a high-yield parking spot with a seven-day hold is not an emergency fund unless another route gives you immediate access.
Track the current balance, available balance, hold expiration, and the time required to move the money back out. A one-week hold going in plus several business days coming out can turn a savings account into a modified short-term CD.
Merchant Compatibility
A bank transfer test is not a bill-payment test.
An external transfer proves that two institutions can exchange an ACH entry. It does not prove that GEICO, a utility, an insurer, or another merchant will accept the routing number, recognize the account number, debit a savings account, or send the debit to the correct share.
Credit unions create additional possibilities: a long member number, a shortened account number, a suffix, or a share number may direct the merchant to a different savings account than the one you intended. Test before trusting an important autopay.
The Field Test
Never trust an untested route.
Testing and documenting each route is how The Art Of BankCraft becomes a working system instead of a theory.
- Link the account and document which method was used.
- Run a small transfer in each direction.
- Record the push limit, pull limit, monthly limit, and transaction-count limit.
- Check how the destination is identified in transaction history.
- Measure when the transfer posts and when the money becomes available.
- Test a merchant withdrawal separately if the account will pay bills.
- Confirm that support can explain the transaction and provide a trace number when necessary.
- Keep another working route before moving a buttload of money.
Access Is Part of the Account
A VPN is not a guarantee against geo-blocking.
When you sign in, a financial institution may evaluate far more than your username and password. It may examine your country, IP address, Internet provider, device, browser, time zone, and whether the connection appears to come from a commercial VPN or hosting network.
Geo-blocking happens when an institution restricts access because of one or more of those signals. A VPN can make your connection appear to originate in the United States, but it does not make the connection invisible. Banks may recognize and block known VPN addresses, and an address that works today may fail tomorrow.
What can fail abroad
- The website may refuse to load or reject the sign-in.
- The mobile app may work differently from the website.
- A bank may accept one VPN server and block another.
- Extra identity verification may depend on a U.S. phone number.
- A familiar device may still be challenged because the network changed.
What to test before leaving
- Website and mobile-app access over both Wi-Fi and cellular data.
- Your VPN, including more than one U.S. server location.
- Two-factor authentication while outside the United States.
- A second institution that does not depend on the same access route.
- A secure backup method you have already tested.
If you cannot reliably reach the account, its APY, transfer limits, and polished app do not matter.
I use both Norton VPN and Bitdefender VPN. My testing from Honduras has produced both outcomes: some institutions allowed normal access, while Vio and Live Oak repeatedly forced me to change VPN servers—and sometimes blocked the VPN connection itself. That does not predict what every bank will do from every country, but it proves why international access belongs in the evaluation.
A VPN encrypts traffic between your device and the VPN provider and changes the network address a website sees. It does not override a bank’s security policy, guarantee account access, or turn an untested institution into a dependable travel bank.
Frequently Asked Questions
BankCraft FAQ
Clear answers to the questions people ask when they begin building a Banking Ecosystem.
What is BankCraft?
BankCraft is the practical skill of choosing financial institutions for their strengths, assigning each one a specific job, connecting them, and building dependable routes for moving and protecting your money. You are not bound to one institution. You build a system in which every institution must earn its place.
What is The Art Of BankCraft?
The Art Of BankCraft is the strategy behind the system. It means understanding regulations, ACH networks, verification methods, transfer limits, holds, fraud controls, and each institution's risk tolerance before moving your money. Learn the terrain. Know your routes. Prepare another route before you need it.
What is a Banking Ecosystem?
A Banking Ecosystem is a group of financial institutions working together under your direction. Think of it as a symphony: one institution may serve as your Anchor, another as your Vault, another as a Specialist, and another as a Bridge. You are the conductor. You decide who plays, what role each institution performs, and when an institution should be replaced.
How many financial institutions do I need?
There is no magic number, but one institution leaves you dependent on one set of rules, limits, and technology. Three well-chosen institutions are a practical starting point: a primary Anchor, a dependable Reserve, and an institution that provides a useful specialty or transfer route. Every account should have a reason to exist.
What is a Bridge institution?
A Bridge is a financial institution that creates a pathway between accounts that cannot connect directly. It may support microdeposit verification, provide stronger ACH capabilities, or connect institutions with incompatible linking systems. A Bridge may not offer the highest interest rate, but the route it provides can make the entire Banking Ecosystem work.
What is the difference between pushing and pulling money?
A push begins at the institution sending the money. A pull begins at the institution receiving it. The same two accounts may have different limits, holds, speeds, and verification requirements depending on which institution initiates the transfer. When one direction is restricted, the other direction may provide a better compliant route.
Are banks the enemy?
No. The banks are not the battlefield. The system is.
Every financial institution operates under its own policies, technology, regulatory responsibilities, fraud controls, and risk tolerance. BankCraft does not mean fighting banks, breaking their rules, or trying to defeat their safeguards. It means understanding the system, working within the rules, and choosing another legitimate route when one path does not meet your needs.
BankCraft Reference
Need a term? We moved the dictionary.
The growing list of BankCraft and banking terms now has its own permanent home. It is easier to scan, easier to update, and easier to link directly from lessons, reviews, and field reports.
BankCraft Glossary
APY, ACH, Bridge, Vault, Financial Symphony, microdeposits, holds, push, pull, settlement, transfer limits, VPNs, and more—all in plain English.
Browse the Glossary →Official References
See how the providers describe their systems.
Ready to build your Financial Symphony?
See how the institutions performed in the field, what chairs they earned, and which ones are still playing.