Save and earn
High APY, reasonable balance rules, no tricks, and access to your money when you need it.
Presented by Digital Banking Nomad
Start here
A practical way to build your own custom financial institution from the products and services that fit your life.
Bank on My Terms is the destination. The BankCraft Method is how you get there.
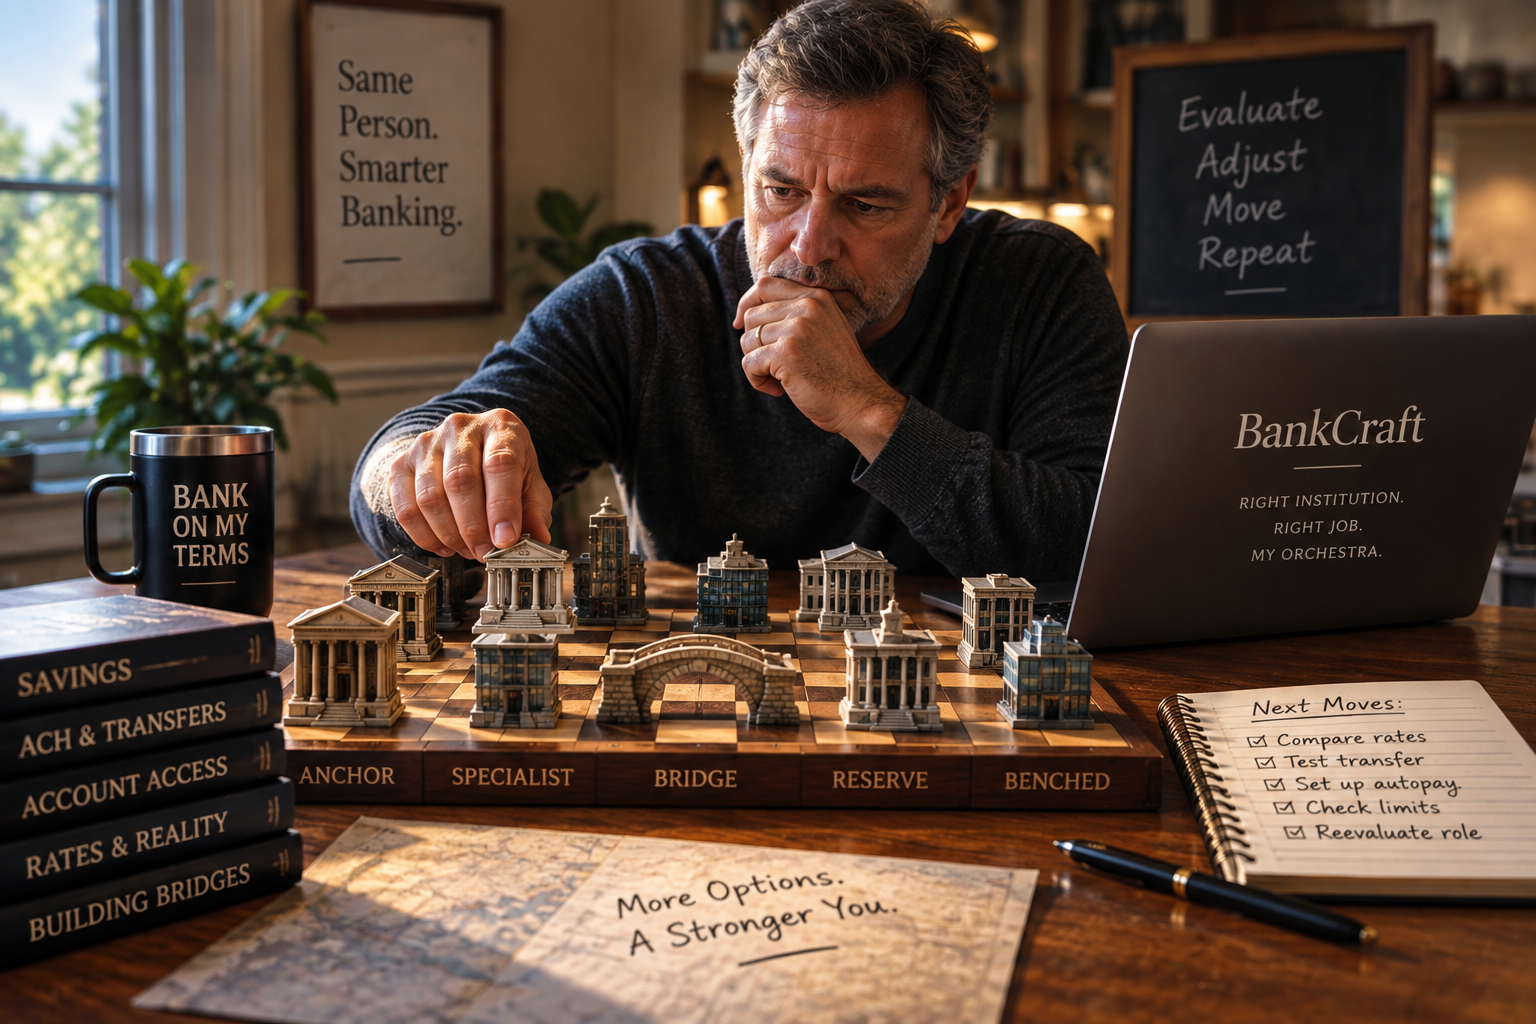
If you could build your ideal financial institution from scratch, what would you put in it?
Before you compare banks, credit unions, APYs, bonuses, apps, branches, or account features, decide what you actually need your banking structure to do.
Maybe you want a strong savings rate. Maybe you need cash deposits, a nearby branch, safe deposit boxes, a notary, a business account, excellent rewards, easy ACH transfers, dependable support, or a mobile app that makes sense. Maybe you need several of those things.
That is where BankCraft begins. You define the jobs first. Then you look for institutions that can do those jobs well.
You are not auditioning for the bank. The bank is auditioning for you.
With the BankCraft Method, a bank or credit union is a candidate for a job in the financial institution you are building. You are the employer. You are the CEO.
If one institution does not open the account, does not offer the product you need, or does not fit the role, the plan does not collapse. You keep scouting. There are other candidates.
There is no universal answer. A brick-and-mortar institution may be important to you because you need cash services, a notary, a safe deposit box, a business relationship, a cashier's check, or a person you can sit across from when something unusual happens.
Someone else may not need a local branch at all. If a digital institution provides the cash access, shared-branch access, ATM network, transfers, and service that person needs, that can work too.
High APY, reasonable balance rules, no tricks, and access to your money when you need it.
Useful ACH limits, dependable linking, sensible transfer timing, and routes to the other institutions on your team.
Cash deposits, notary access, safe deposit boxes, cashier's checks, branches, business services, or shared-branch access.
Good cards, useful rewards, merchant payments, strong mobile and desktop access, and customer service you can actually reach.
Before anything else, check the basic account cost. A credit union may require a small membership share or a qualifying membership path. That is different from paying an ongoing monthly service or maintenance fee just to keep a deposit account open.
If the basic relationship costs money every month just for existing, we keep shopping.
Start on the institution's website. Do not let a bright APY, bonus, or reward headline make the decision for you. Find the actual requirements.
Check balance caps, direct-deposit rules, transaction requirements, temporary promotional periods, and what happens above the advertised tier.
If you are building a team of institutions, money has to move between the players. Check daily, weekly, and monthly limits when available.
Look at branches, ATMs, cash deposits, shared branching, transfer methods, merchant pulls, debit access, and withdrawal rules.
Look at the website, mobile app, login process, support channels, security setup, and whether the institution gives you the information you need.
Banking websites can bury important information under disclosures, rate tables, account agreements, fee schedules, and jargon. If you can read and understand all of it yourself, great. If you cannot, or you simply want another set of eyes, AI can help turn it into plain English.
Tell the AI what you are looking for and give it the institution's information. Ask: Is this APY for real? Is there a catch? Are there balance limits? Do I need direct deposit? Is there a monthly fee? What hoops do I have to jump through? What are the ACH limits? Based on the job I need filled, does this account appear to fit?
You can also give AI an institution's fee schedule, disclosure, account agreement, or other PDF and ask it to summarize the parts that matter to you. You can even give it your requirements and ask it to help scout institutions that may deserve a closer look.
AI is a helper, not the bank and not the final authority. It can misunderstand something or make a bad assumption. Verify important rates, fees, limits, eligibility requirements, and account terms against the institution's current website, disclosures, or staff before making a decision. And remove account numbers, Social Security numbers, passwords, PINs, card numbers, security codes, and other sensitive information before uploading anything.
BankCraft does not tell you to move $20,000 into a new account just to find out whether you like it. Many institutions let you take a useful look with little or no money at risk.
You may be able to open an account and inspect the website and app before making a meaningful deposit. In other cases, put in $5, $25, $50, or another amount you are comfortable having in play.
Then test something real. Move $5 to your brick-and-mortar institution. See how long it takes. Move it back. Watch how pending transactions appear. Check the mobile app. Check the desktop site. See what happens over a weekend. Learn how the institution behaves before you give it an important job.
You do not have to risk a large amount of money to learn how an institution works.
Describe your ideal banking structure in terms of jobs, not institution names.
Look across local banks, credit unions, online banks, and other legitimate financial institutions.
Check fees, APY rules, limits, access, support, technology, membership requirements, and how the product really works.
Use small amounts and real transactions to learn how the institution behaves.
Hire the institution for the job it has earned, not for every job simply because the account is open.
Make sure the institutions can move money and work well with the other players in your structure.
Rates, limits, policies, service, and technology change. Keep watching the job performance.
If the institution no longer fits the job, change the assignment. You are not trapped.
You may discover an institution while shopping for one product and find that another product is what really earns it a role. That is not a mistake. That is scouting.
A local credit union might earn a role because of its branch access. Another institution might earn a role because of its savings rate. Another may be the strongest way to move money between the others.
A dependable central institution that handles important everyday banking well.
An institution kept because it performs one particular job exceptionally well.
An institution currently doing useful work in your banking structure.
A useful backup that may not be doing much today but has a reason to remain available.
An institution that helps create dependable routes for moving money between other institutions.
An institution that is no longer trusted with an active assignment but may not need to be closed immediately.
If you were hiring people to work for you, you would make sure they could do their own jobs. You would also want to know whether they could work well with each other.
Financial institutions are no different. A great savings account that cannot move money where you need it may be a poor fit for the role you had in mind. If you are building your own financial institution, the players have to be able to move money between one another.
That is why BankCraft pays attention to ACH limits, account linking, micro-deposits, transfer timing, merchant pulls, pending balances, and whether an institution plays well with others.
Every institution has its own account terms, transfer limits, risk controls, membership rules, technology, and operating policies. The BankCraft Method does not entitle you to change those rules.
Work within the institution's rules. If the rules do not fit the role, change the institution, not the rules.
Do not fight a square peg into a round hole. Thank the institution, change the assignment, or find another candidate.
You do not need to read every lesson before you begin. You do not have to pass a test, recite a pledge, stand on one foot, or cover one eye before you are allowed to start.
The Classroom is there when you reach a particular decision. Shopping for a high-yield account? Use the lessons that help you examine APY requirements and spot shiny catnip. Moving money? Use the ACH and Bridge lessons. Wondering whether two institutions will work well together? Use the lessons about account linking and playing well with others.
The Method gives you the structure. The Classroom helps you solve the problem in front of you.
Building a banking structure around your needs is a process. Give yourself time to see how an institution handles real transactions, weekends, holds, support, app changes, transfer limits, and the ordinary problems that do not show up on the marketing page.
Start with one need. Solve one problem. Add responsibility only when an institution has earned it. Your structure can grow and change with you.
If you want to walk into a nearby bank, open an account, and be done with it, there is nothing wrong with that.
BankCraft is for the person asking a different set of questions: What would my ideal banking structure look like? What jobs do I need performed? Which institution is best at each job? How do I test it without moving my whole financial life? How do I connect the pieces? How do I replace one piece without tearing everything apart?
That is the BankCraft Method. Scout. Investigate. Test. Connect. Monitor. Adjust. Trust the process.
You are not trying to find one perfect bank. You are building a system in which each institution earns a role and works with the others.
After all this is said and done, you should have your own BankCraft Financial Symphony.
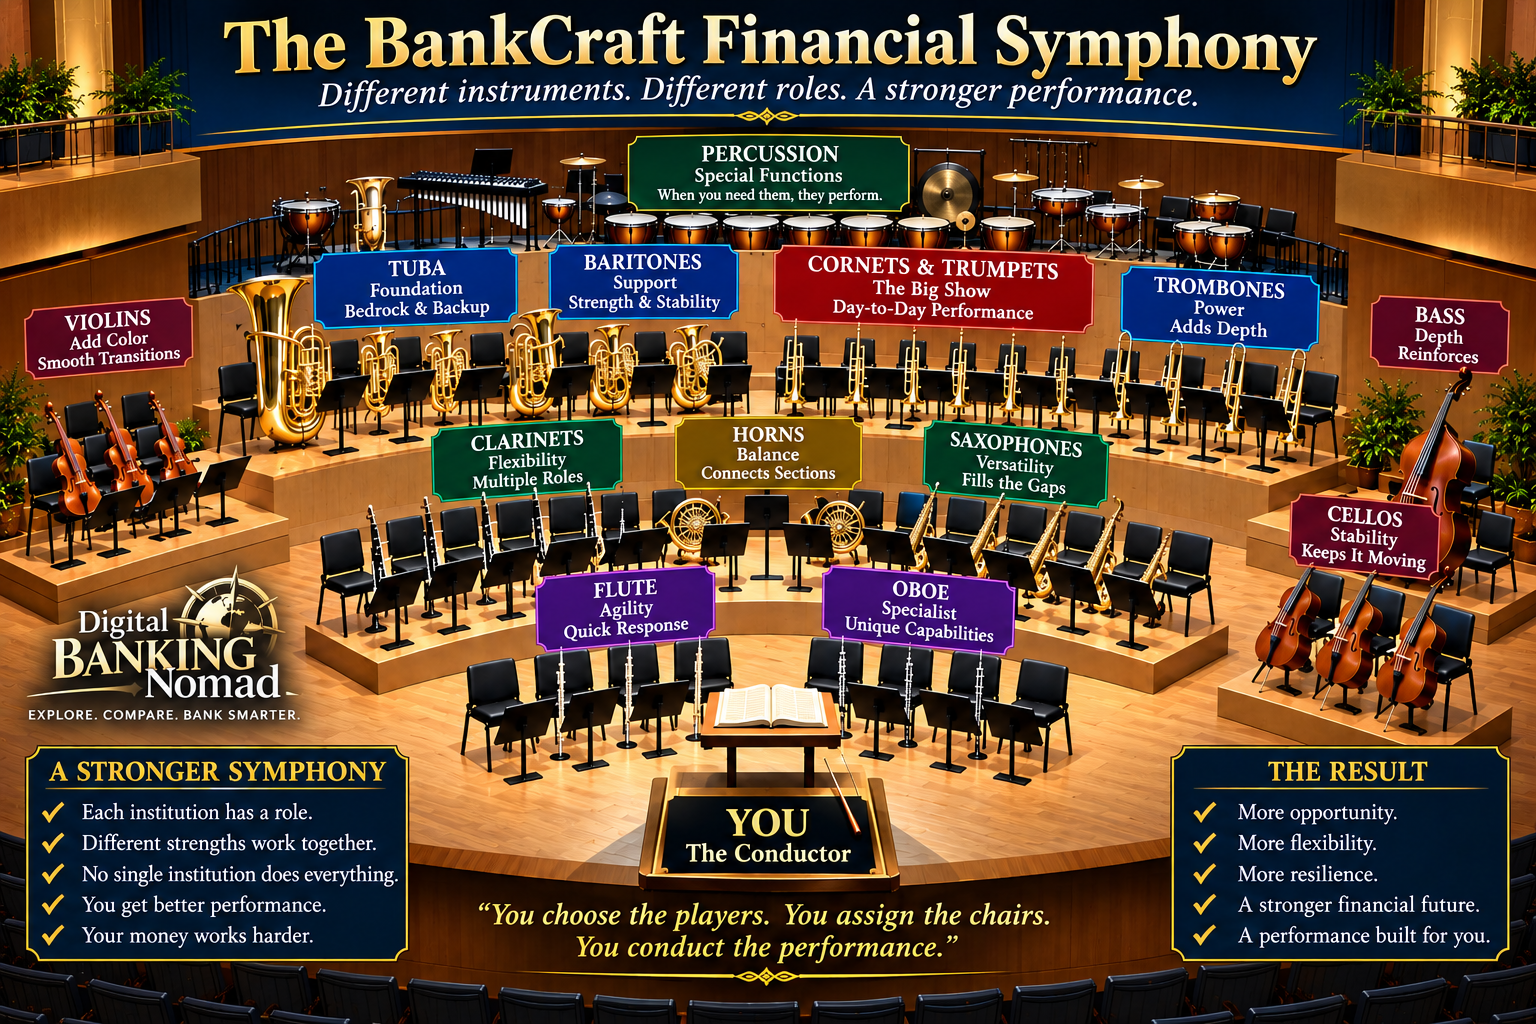
You are the conductor. The institutions perform the roles you assign.
BankCraft is the discipline. The BankCraft Method is how you build it. The Classroom helps you along the way.
As you define what you want, scout the candidates, test them, assign the jobs, connect the players, and keep only what earns its place, you reach the point where you can say:
“I now bank on my terms.”