The Art of BankCraft™
BankCraft Classroom
When the Bank Says No
Account denials, identity reviews, transfer holds, frozen accounts, restrictions, and closures.
Last reviewed: September 5, 2026
There are two very different ways to hear “no.”
Before you get inside
You apply for an account and the institution declines the application. A checking-account consumer report, identity-verification problem, eligibility rule, or the institution’s own decision may be involved.
After you are already inside
The account opens, but a transaction triggers a hold, review, restriction, freeze, or closure. Now your existing money, payments, and transfer routes may be affected.
Those are not identical problems. One concerns whether the institution will begin the relationship. The other concerns what the institution will permit after the relationship begins.
Banks have consumer reports too.
Experian, Equifax, and TransUnion are the names most people associate with consumer reporting. Banks and credit unions may also use specialty checking-account reports when deciding whether to open a deposit account.
ChexSystems collects and reports information about checking-account applications, openings, closures, and reasons for closure. Early Warning Services also provides deposit-account screening information used by financial institutions.
These reports are not ordinary credit scores. They may contain information involving unpaid negative balances, involuntary closures, suspected fraud, account abuse, identity information, applications, or prior account history. An error can follow you into the next application even when your traditional credit score looks excellent.
You can request your reports.
You have the right to request a free checking-account consumer report every 12 months. If an institution denied an account based in whole or in part on one of these reports, you are also entitled to a free copy of the report used in that decision.
Read the adverse-action notice.
If a bank or credit union denies an account based in whole or in part on a checking-account consumer report, it must provide an adverse-action notice identifying the reporting company and giving its contact information.
The reporting company did not make the final decision. It supplied information. The financial institution used that information as part of its decision. That is why a proper dispute may need to go in two directions:
- Dispute inaccurate information with the consumer reporting company that compiled the report.
- Dispute the same inaccurate information with the bank, credit union, or company that furnished it.
Keep the notice, request the report, mark the exact item you challenge, attach supporting records, and retain proof of when and where the dispute was sent.
No notice does not automatically mean somebody broke the law.
The adverse-action requirement discussed here applies when a consumer report contributed to the denial. An institution may decline an application for another reason, and it may not give you its complete internal risk analysis.
Where you apply can become part of the application.
An institution may advertise online account opening and still have trouble verifying an applicant who is outside the United States. Your physical location, device, telephone number, address, identification, and other application details may not fit the institution’s automated verification process.
That does not prove that a foreign location caused a denial. It means eligibility on paper and successful identity verification from another country are not the same thing.
Field example: applying from Honduras
I applied to two institutions while I was in Honduras, and both applications were denied. I no longer remember which two institutions they were, and I cannot prove that my foreign location caused either decision. The experience taught me to ask a more basic question before starting another application: will this institution accept and verify me from where I am right now?
Do not use a VPN or remote computer to make the application appear to come from a location different from your own unless the institution specifically tells you that method is acceptable. Call through a verified number, explain that you are abroad, ask what identification and location rules apply, or wait until you are physically back in the United States.
Before applying, verify membership and geographic eligibility, identification requirements, telephone requirements, and whether the institution accepts applications from your present location.
For travel preparation and remote-access testing, see Access Is Part of the Account.
A buttload of applications can work against you.
BankCraft encourages using several institutions for different jobs. That does not mean opening everything you see in one weekend.
Specialty reports may include account applications and openings. Institutions also use their own identity, fraud, and risk systems. Several applications may create additional inquiries or application records, depending upon the institution and reporting system. An inquiry is not the same thing as an unpaid balance, involuntary closure, or fraud marker, and there is no universal published rule that two or three denials automatically put somebody on a blacklist.
I have opened six or seven accounts without discovering a problem in a checking-account report. My strong credit may have mattered at an institution that checked it, but that does not prove credit protected me. Deposit-account screening is separate from an ordinary credit score, and different institutions use different information and standards.
Open deliberately. Test completely. Give the account a job before auditioning the next one.
The account opened. Then the bank hit the brakes.
A working account can encounter a deposit hold, transfer review, identity request, restricted feature, frozen balance, or sudden closure. The trigger may involve suspected fraud, unusual activity, an information mismatch, a legal order, an error, or the institution’s interpretation of its account agreement and risk obligations.
Start by identifying the scope. Is one deposit unavailable? Is one transfer pending? Is online access blocked while the account remains open? Is the entire account restricted? Has the institution announced a closure and explained how the remaining balance will be returned?
Do not use the words hold, review, freeze, and closure as though they mean the same thing. The correct response depends upon what has actually been restricted.
Ask operational questions.
- What exactly is restricted?
- What documents or verification can I provide?
- Is there a case or reference number?
- What happens to incoming deposits and scheduled payments?
- If the account is closing, how and when will the remaining balance be returned?
Field example: Abound asked what job it was performing.
This example records D.B. Nomad’s experience in August 2026. It is not a prediction of how Abound Federal Credit Union or another institution will handle a different member or transaction.
I deposited an amount into Abound and then moved half of it onward to another institution. That activity triggered a risk review, and my account was locked.
When I called, I explained that I was developing a banking-education website and evaluating how different institutions could work together. I was not collecting accounts without a purpose. I was building a banking ecosystem—a Financial Symphony in which every institution had a specific job.
Abound had earned an important place in that ecosystem. Another institution could hold the money but could not perform certain payments I needed. Abound could. Abound also supported microdeposit verification, which gave me a reliable path to a Vault that was difficult to reach through other institutions.
I explained where the money came from, where it was going, that every account involved belonged to me, and why Abound was part of the route. Once the representative understood the legitimate job Abound was performing within my ecosystem, the account was reopened that same day.
Some institutions may never ask for an explanation before restricting or closing an account. Abound gave me an opportunity to explain the activity, and I was prepared to do it.
A straightforward explanation you can adapt
“I use several financial institutions to create a banking ecosystem—a Financial Symphony in which each institution performs a specific job. I am currently evaluating what role your institution can perform in that ecosystem.
“The account holding my money cannot connect directly to the institution where I need to send it. Your institution can connect to both, which allows it to perform the role of a Bridge. The money came from an account I own, passed through my account at your institution, and was going to another account I own. I can provide records showing the complete route and my ownership of each account.
“If using the account this way complies with your rules, I would like to continue using your institution as a Bridge. If it does not, please tell me which transfer methods are permitted. I will stop using this route and reevaluate what legitimate role your institution can perform in my banking ecosystem.”
A legitimate transaction is easier to explain when every institution has a job and the route was documented before somebody asked.
Do not drive around the barrier.
If a transaction or account is held for review, resolve that review with the institution before attempting an alternative route. Do not split, restructure, repeat, or reroute transactions for the purpose of avoiding an institution’s controls or reporting requirements.
If the institution completes the review and tells you that it will not support the activity, accept that answer. Move forward using permitted methods and an institution whose rules fit the legitimate job your banking ecosystem needs performed.
This is the same guardrail used in Building Bridges: alternate routes make the Financial Symphony more resilient, but they are not escape lanes around an unresolved review.
For the difference between legitimate staged ACH transfers and arranging transactions to evade required reporting or recordkeeping, see The Elephant in the Room: Routing or Structuring?
The bank may not tell you everything.
An institution may be unable or unwilling to reveal its complete fraud or compliance analysis. Federal law also prohibits a financial institution from disclosing a Suspicious Activity Report or information that would reveal whether one exists. Ask what you can provide and what happens next; do not assume you are entitled to every internal detail.
Your paper trail is part of the banking system.
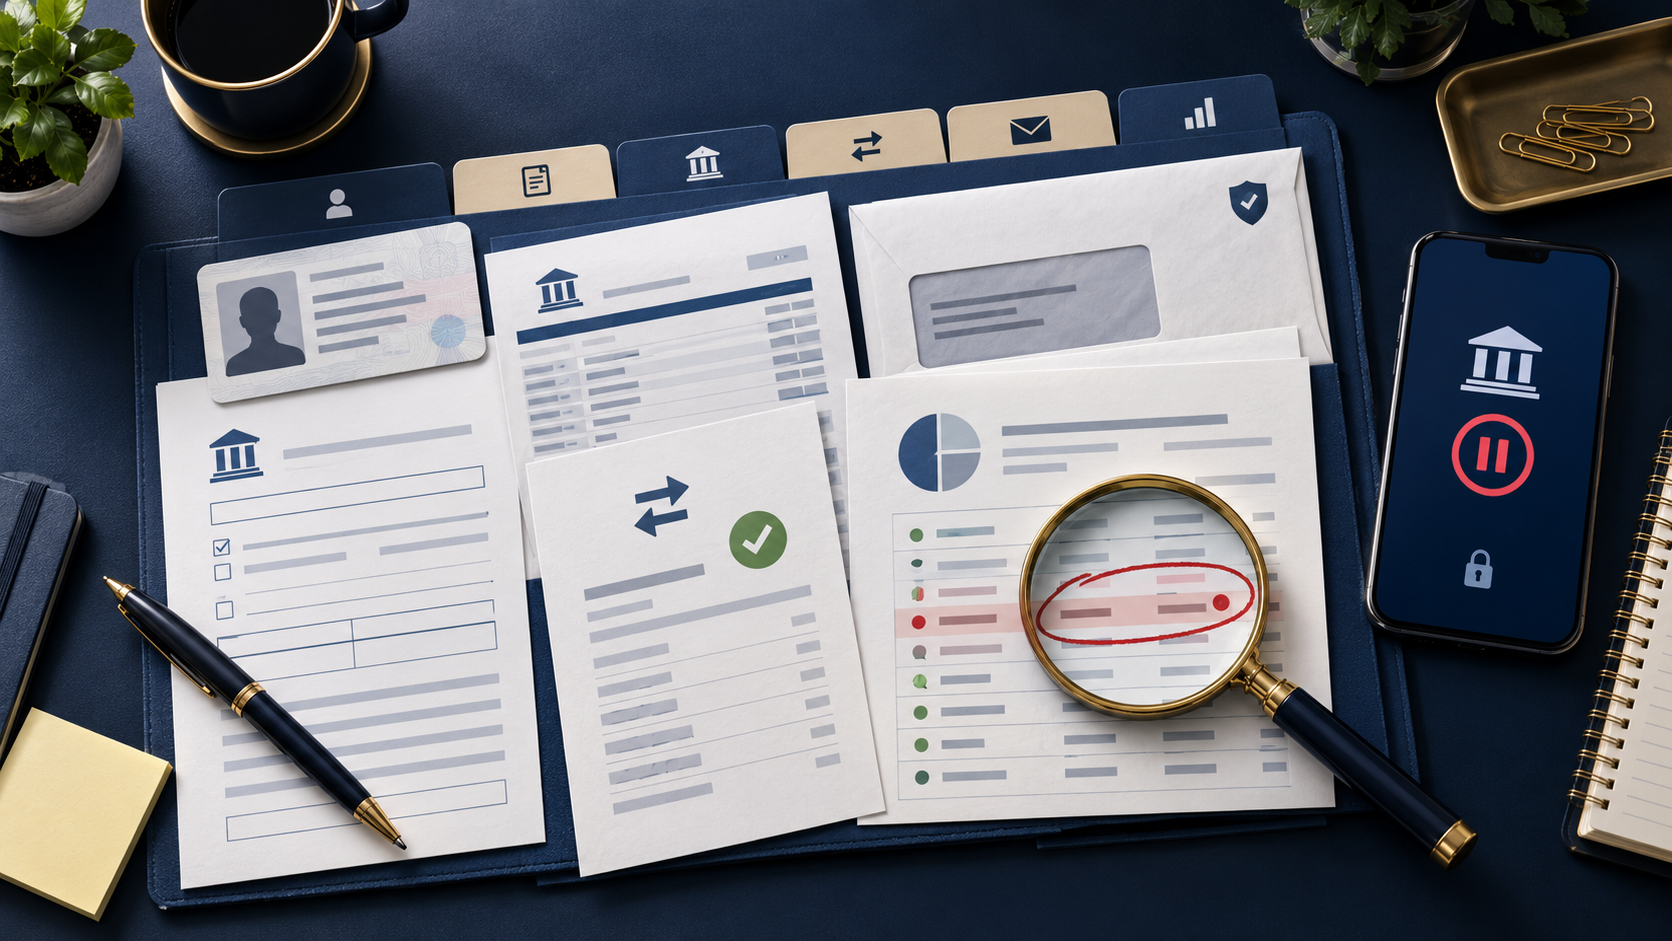
Maintain enough information to reconstruct what happened:
- Application confirmations and adverse-action notices
- Account agreements and closure notices
- Transfer confirmations, dates, amounts, directions, and ownership of both endpoints
- Screenshots showing holds, restrictions, or error messages
- Case numbers, call dates, representative names, and promised next steps
- Copies of identity documents submitted through verified channels
- Consumer reports, disputed entries, supporting evidence, and delivery confirmation
Verify the channel before sending identity documents.
Do not send a driver’s license, Social Security card, bank statement, or verification code merely because an email, text, or caller requested it. Reach the institution through its official application, website, card number, or published telephone number.
Cooperate first. Escalate with a record.
Begin with the institution. Use its formal customer-service, fraud, dispute, or executive-resolution channel as appropriate. State the problem, the result you need, the evidence you have, and the response deadline you were given.
If the institution does not resolve the matter, identify the correct regulator. The FFIEC Consumer Help Center can help locate the federal regulator for a bank. Credit-union complaints may go through the NCUA Consumer Assistance Center. The Consumer Financial Protection Bureau accepts complaints and may route them to the company or another agency.
A regulator can review whether an institution followed applicable requirements. Filing a complaint does not guarantee that the regulator will force an institution to reopen an account, restore a transfer feature, or continue the banking relationship.
A complaint should be factual. Include the dates, amounts, case numbers, documents provided, answer received, and specific unresolved problem. “They made me mad” is understandable. It is not the strongest case file.
BankCraft Protocol
When the Bank Says No
Stop. Do not repeat, split, or reroute a transaction while a review remains unresolved.
Identify. Determine whether this is an application denial, consumer-report issue, identity request, transaction hold, account restriction, freeze, or closure.
Document. Preserve the notice, screen, amount, date, route, account ownership, case number, and every requested item.
Respond. Use a verified channel. Supply relevant records, correct inaccurate information, and ask what happens next.
Escalate. If the institution does not resolve the issue, present a factual record through its formal complaint process and then to the appropriate regulator.
Official references and action tools
- CFPB: Why was I denied a checking account?
- CFPB: Requesting a checking-account consumer report
- CFPB: Disputing a checking-account report error
- CFPB: Chex Systems, Inc.
- CFPB: Early Warning Services, LLC
- OCC: When a bank closes a checking account
- FinCEN: Suspicious Activity Report confidentiality
- FFIEC: Consumer Help Center
- CFPB: Submit a complaint
- NCUA: Consumer Assistance Center complaint
- Federal Trade Commission: IdentityTheft.gov