The Art of BankCraft™
BankCraft Classroom
The Elephant in the Room: Routing or Structuring?
Moving your own money through legitimate Bridges without confusing transfer planning with evasion.
Published and reviewed: September 5, 2026
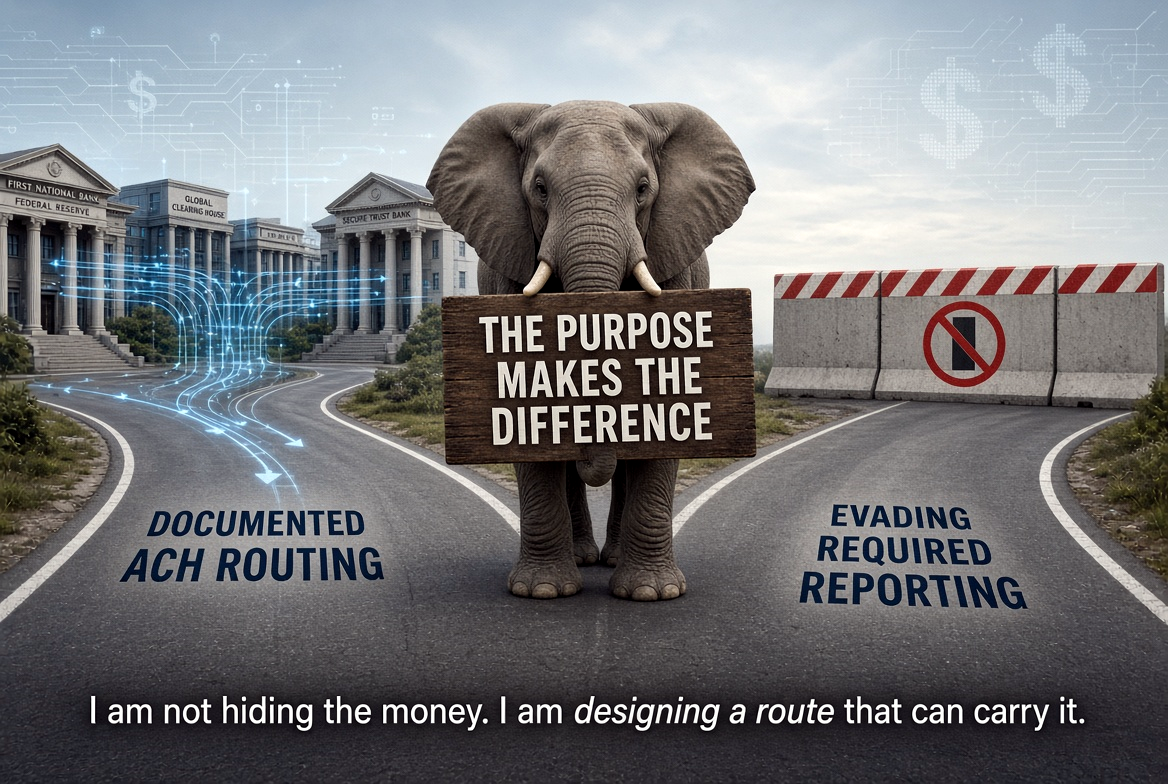
The same word is doing two different jobs.
In ordinary conversation, people structure plans, businesses, schedules, and routes. In BankCraft, the better word is routing. Think of a railroad switch yard: one train moves onto this track, another moves onto that track, and each switch sends the cargo along a route capable of carrying it to its destination. A banking ecosystem works the same way. Money may travel through several institutions because no single track connects the starting point directly to the destination.
Banking law uses structuring as a term of art. Under the federal definition used for Currency Transaction Report requirements, structuring occurs when somebody conducts one or more transactions in currency for the purpose of evading required reporting. The regulations define a transaction in currency as involving the physical transfer of currency. A bank check, wire transfer, or other written transfer without physical currency is not a currency transaction for that purpose.
Do not stretch that distinction too far.
This lesson addresses ordinary ACH routing compared with classic cash structuring. Federal law also prohibits attempts to evade certain other Bank Secrecy Act reporting and recordkeeping requirements. No payment method grants permission to conceal activity, misstate facts, or defeat a legally required record.
I am not hiding the money. I am designing a route that can carry it.
The purpose makes the difference.
Documented ACH routing
Existing funds move electronically between accounts you own because the institutions cannot connect directly or because published transfer limits require stages. The route, ownership, and purpose can be documented.
Illegal structuring
Transactions are divided or arranged for the purpose of causing a required report or record not to be created, or to contain a material omission or misstatement.
| Example | What it is |
|---|---|
| Routing money from Institution A through a Bridge to Institution C because A and C cannot connect directly. | Bridge routing. The middle institution provides a connection the other two lack. |
| Sending several ACH transfers because a published per-transfer, daily, or monthly limit prevents one larger transfer. | Staged transfer planning. Each transfer remains within the institution’s stated terms. |
| Choosing an amount below the maximum so several routes can be reconciled without accidentally exceeding an aggregate limit. | Operational control. A maximum is a ceiling, not a required transfer amount. |
| Dividing physical cash transactions for the purpose of preventing a required Currency Transaction Report. | Structuring. The purpose is evading legally required reporting. |
| Sending a replacement transaction through another route while the original transaction remains under review. | The wrong response. Resolve the existing review before choosing another permitted route. |
A transfer limit is a ceiling, not an assignment.
A transfer limit establishes the most you may move. It does not establish the amount you must move. Within the institution’s individual and cumulative limits, the transfer amount is your choice.
You may choose a lower amount to maintain control, reconcile several transfers, manage different Bridges, reduce the damage from your own possible error, or avoid accidentally exceeding a daily or monthly limit. Computers record every ACH transaction. Choosing a smaller permitted amount does not make the transaction invisible.
An ordinary ACH transfer creates electronic records at the sending and receiving institutions. Those records do not make every transaction immune from review, but they give you a traceable route that cash does not provide.
Choosing a lower permitted amount for control, reconciliation, or route management is legitimate transfer planning.
When somebody at the institution says, “We think you are structuring.”
Imagine a police officer walking up to my window after pulling me over and asking, “Mr. Nomad, do you know what you were doing?” My answer would be, “Officer, with all due respect, the more important question is: What do you think I was doing?” That is the salient question, because I cannot respond intelligently until I know what the officer believes he observed.
The same principle applies when a bank or credit union questions a transfer pattern. I know that I was routing my own documented money through a switch yard of institutions. The institution may see something different. I cannot control its first impression. I can ask what it believes it observed, then explain exactly what I did, why I did it, and why I selected that route and those amounts.
Do not panic, confess to something you did not do, or begin an argument about federal law. First ask the institution to define its concern.
Start with this question
“When you use the word ‘structuring,’ are you referring to structuring as defined under federal reporting and recordkeeping law, or are you describing an internal concern about how I am using the account?”
Then ask:
- Which transactions concern you?
- Is the concern the amount, frequency, route, destination, or something else?
- What required report or record do you believe I was attempting to avoid?
- Are you questioning whether I own the originating or destination accounts?
- Can I provide statements showing the source, route, and ownership of the funds?
- Does the account agreement prohibit using this account to transfer money between other accounts I own?
- If the activity is not supported, what transfer activity does the institution permit?
They may not tell you everything.
An institution may be unable or unwilling to reveal its complete fraud or compliance analysis. Federal law prohibits a financial institution from disclosing a Suspicious Activity Report or information that would reveal whether one exists. Ask for the information it can provide and concentrate on documenting the legitimate activity.
BankCraft may call it routing. The institution may call it a pattern. The conversation begins by finding out what the institution believes the pattern means.
A straightforward explanation you can adapt
“This was not a cash transaction. The funds already existed in an account that I own. They were electronically transferred by ACH into my account at your institution, and I intended to transfer them onward to another account that I own.
“I use several financial institutions to create a banking ecosystem—a Financial Symphony in which each institution performs a specific job. The originating and destination institutions cannot connect directly, but your institution can connect to both. That allows this account to perform the role of a Bridge.
“I conducted the transfers within the limits your institution established. I may choose an amount below the maximum so I can track transfers across several institutions without exceeding a daily or monthly limit or accidentally duplicating a transfer.
“I can document the originating account, the receiving account, my ownership of both accounts, and the complete movement of the funds. I was not attempting to prevent a report, conceal the source of the money, or avoid required recordkeeping.
“If using the account this way complies with your rules, I would like to continue using your institution as a Bridge. If it does not, please tell me which transfer methods are permitted. I will stop using this route and reevaluate what legitimate role your institution can perform in my banking ecosystem.”
Field example: Abound asked what job it was performing.
This example records D.B. Nomad’s experience in August 2026. It is not a prediction of how Abound Federal Credit Union or another institution will handle a different member or transaction.
I deposited an amount into Abound and then moved half of it onward to another institution. That activity triggered a risk review, and my account was locked.
I explained that I was developing a banking-education website and evaluating how different institutions could work together. I was building a banking ecosystem—a Financial Symphony in which every institution had a specific job.
Abound had earned an important place. Another institution could hold the money but could not perform certain payments I needed. Abound could. Abound also supported microdeposit verification, giving me a reliable path to a Vault that was difficult to reach through other institutions.
I explained where the money came from, where it was going, that every account belonged to me, and why Abound was part of the route. Once the representative understood the legitimate job Abound was performing, the account was reopened that same day.
A legitimate transaction is easier to explain when every institution has a job and the complete route was documented before somebody asked.
The institution can decline the role.
You may document every dollar, own every account, follow every published transfer limit, and provide a completely legitimate explanation. The institution may still decide that it does not want its account used as a Bridge.
The explanation gives the institution facts. It does not force the institution to accept the activity. Subject to its agreement and applicable law, an institution may restrict activity or close an account. It is their institution, and access to its ACH service is governed by its rules.
If the answer is no, do not fight to force the institution into your Financial Symphony. Ask:
- Is the decision final, and when does it take effect?
- May I transfer the remaining balance by ACH to another account I own?
- If ACH is unavailable, how will the remaining balance be returned?
- Will the institution waive any outgoing-transfer or official-check fee?
- What happens to pending transfers, incoming deposits, and scheduled payments?
- How can I obtain final statements and written confirmation that the account is closed?
Then redirect deposits and payments, preserve the records, retrieve the remaining money through an approved method, and retire the institution from that role.
An institution may decline the job. BankCraft’s answer is a documented exit—not an argument or an escape route around an unresolved review.
Routing belongs to a larger system.
Use this lesson with Can Your Money Get In—and Back Out?, The ACH Red Zone, Building Bridges, and When the Bank Says No.
BankCraft Protocol: Document the Route
Name the purpose. Know why the money is moving and what job each institution performs.
Verify the route. Confirm ownership, connections, permitted transfer methods, and individual and cumulative limits.
Choose the amount. Treat the maximum as a ceiling. Select an amount you can control, reconcile, and document.
Record every stage. Preserve confirmation numbers, dates, amounts, sending accounts, receiving accounts, and pending transactions.
Ask what they mean. If somebody says “structuring,” determine whether the concern involves federal reporting, recordkeeping, account ownership, or internal account-use policy.
Resolve before rerouting. Do not repeat, split, or redirect a transaction while it remains under review.
Accept the answer. If the institution declines the Bridge role, retrieve the money through an approved method and redesign the route.
Official references
- FFIEC: Structured Transactions and Currency Transaction Report requirements
- FFIEC: Definition of structure or structuring
- 31 CFR 1010.100: Definitions of structuring and transaction in currency
- 31 U.S.C. 5324: Structuring transactions to evade reporting requirements prohibited
- FFIEC: Suspicious Activity Reporting
- FinCEN: Suspicious Activity Report confidentiality
- OCC: When a bank closes a checking account
Educational information only. This lesson explains general banking concepts and does not provide legal advice about a particular transaction or investigation.